

US bond yields are moving higher. FII
The US dollar remains central to global capital flows, and that changes the equation for investors across markets. For an Indian investor, the impact can reach far beyond the US Treasury market.
Higher US yields can make fixed income more attractive, support the dollar, influence FII flows, put pressure on the rupee and raise the rate used to value equities.
At the same time, US companies continue to report strong earnings, while India has a strong long-term growth story alongside higher energy costs, FII selling pressure and elevated valuations.
So the important question is:
What does a higher-rate world mean for India, the US and the way you build your portfolio?
What are we covering today?
- Why rising US yields affect global capital flows and FII activity
- What higher rates mean for US stocks and AI valuations
- Why US equity exposure still matters for Indian investors
- How India’s growth story is being tested by valuations and macro pressure
- How India and the US can play different roles in a portfolio
- What investors can consider across equities, global assets and debt
1. When rates rise, which market gets the money?
Start with the basic transmission mechanism:
US rates ↑ → bond yields ↑ → dollar attractiveness ↑ → global capital allocation changes
The US 10-year Treasury yield stood at approximately 4.96% on 11 September 2026, compared with around 4.01% a year earlier.
The move has been gradual but meaningful:
- February 2026 low: 3.94%
- Three-month change: approximately 25 basis points
- Six-month change: approximately 30 basis points
- One-year change: approximately 95 basis points
A basis point is one-hundredth of a percentage point. Therefore, a 25-basis-point move equals 0.25 percentage points.
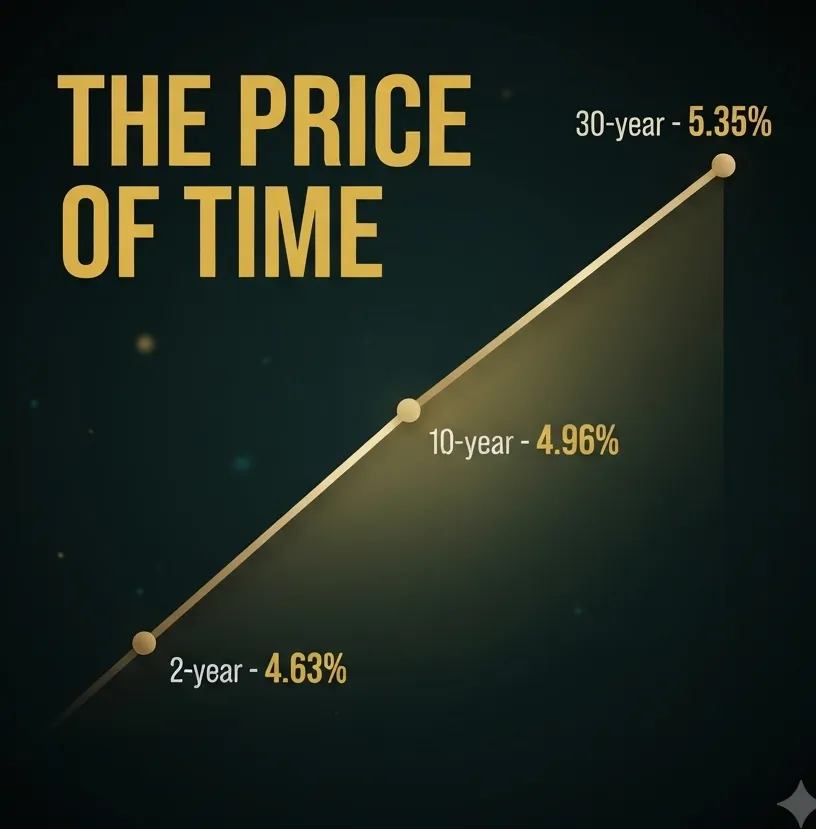
The yield curve also shows that investors are demanding higher returns for holding longer-term US government debt:
| Treasury maturity | Yield |
|---|---|
| 2-year | 4.63% |
| 10-year | 4.96% |
| 30-year | 5.35% |
The 2-year to 10-year spread is around 0.33 percentage points, while the 10-year to 30-year spread is around 0.39 percentage points.
Why are yields rising?
The reason behind the move matters.
The 10-year nominal yield is around 4.96%, while the real yield on inflation-protected Treasuries is approximately 2.50%. The 10-year breakeven inflation rate is around 2.40%.
This suggests that the recent rise is being driven heavily by higher real rates and term premiums.
The term premium is the additional return investors demand for holding longer-duration bonds amid uncertainty around inflation, government borrowing and future interest rates.
The US fiscal position is also adding pressure. The FY2026 federal deficit is projected at approximately $1.9 trillion, or 5.8% of GDP, compared with a 50-year historical average of around 3.8%.
Federal debt held by the public is expected to reach approximately 101% of GDP in 2026.
Higher borrowing requirements mean the Treasury needs to issue large amounts of debt. When supply rises faster than natural demand, investors may demand higher yields before purchasing those bonds.
For Indian investors, the chain is important.
When US government bonds offer close to 5% for a 10-year maturity, global investors have another relatively low-risk destination for capital. That can reduce the relative appeal of emerging-market assets at the margin and influence FII allocation decisions.
FII flows are not driven by one variable alone. Investors compare:
- US Treasury yields
- Currency expectations
- Emerging-market valuations
- Corporate earnings
- Political and macroeconomic risks
- Relative returns across equities and debt
Higher yields also raise the discount rate used to value stocks.
The discount rate is the return investors require today for receiving uncertain cash flows in the future. When that rate rises, the present value of distant earnings falls, particularly for expensive growth companies.
This is why a move in US bond yields can affect Indian equities even when the underlying change begins in the US fixed-income market.
2. What happens to US stocks when bond yields rise?
Two forces are working against each other.
Higher bond yields increase the return available from fixed income and raise the discount rate applied to future earnings. Real estate, utilities and high-multiple growth stocks are particularly sensitive to higher real yields.
Strong corporate earnings, however, can support equity prices even when interest rates rise.
The S&P 500 is trading at a forward price-to-earnings multiple of approximately 19.36x to 24.59x, depending on the earnings calculation used. Its expected one-year nominal earnings growth is around 17.9%.
Profit margins have remained resilient, supported by large technology companies, operating efficiency and strong cash generation.
The key US equity question is:
Can earnings growth continue to justify valuations when the cost of capital is higher?
Investors need to track:
- Revenue growth
- Profit margins
- Free cash flow
- AI-related investment
- Productivity gains
- Treasury yields
- Valuation multiples
A higher valuation can be supported when earnings and cash flows grow consistently. But when the cost of capital rises, investors may become less willing to pay a premium for growth that is expected several years into the future.
The AI earnings reality check
The AI investment cycle is supporting demand for cloud infrastructure, semiconductors and data centres.
Microsoft, Alphabet, Amazon and Meta have reported strong demand linked to cloud and AI infrastructure. AI-related capital expenditure has reached approximately 25% to 30% of total capital outlays for major hyperscalers.
Revenue from cloud infrastructure is visible today. The full return from AI software, automation and productivity gains may take longer to appear in profit margins and free cash flow.
Investors should track the relationship between:
AI spending → revenue growth → operating margins → free cash flow
The difference between spending and realised earnings is important. Companies may invest heavily in infrastructure today, while the resulting productivity gains and software monetisation emerge over a longer period.
Higher rates can make this gap more important because investors have less patience for earnings that remain far into the future.
Financials and energy companies can respond differently. Banks may benefit from stronger interest income, while energy companies can benefit from firm commodity prices.
This means the impact of higher yields is not uniform across the market. Business models, balance sheets, pricing power and cash-flow visibility continue to matter.
3. The US market has something India doesn’t
Higher yields can make US bonds more attractive, but the case for US equities depends on the businesses behind the market.
US markets provide access to companies operating at enormous scale across:
- AI infrastructure
- Semiconductors
- Cloud computing
- Global software
- Digital advertising
- Consumer platforms
- Healthcare innovation
India has strong businesses across financial services, consumption, manufacturing, infrastructure and technology services. However, comparable Indian businesses do not exist at the same scale in several areas of the global technology economy.
An Indian investor buying US equities gains exposure to business earnings, long-term growth and the US dollar.
The currency component matters.
The rupee has depreciated by approximately 10% to 11% over the past year, with USD/INR trading around ₹95.55 on 12 September 2026. The rupee is down approximately 6% year to date.
For an unhedged Indian investor, a weaker rupee can increase the rupee value of US investments.
For example, if a US index rises 10% in dollar terms and the rupee depreciates 8% against the dollar, the approximate rupee return becomes:
10% + 8% = 18%
The exact return will differ because currency and market movements compound, but the direction is clear.
Dollar exposure can therefore provide a useful portfolio cushion when the rupee is under pressure.
This does not mean currency depreciation automatically creates wealth. A weaker rupee can increase the rupee value of overseas assets, but it can also raise India’s import costs, especially when crude oil prices are elevated.
For investors, the point is to understand that US equity exposure has two components:
- The performance of the underlying investment in dollar terms
- The movement of the dollar against the rupee
Both can influence the final return.
Want to invest in US markets from India?
If you’d like to invest in US indices such as the S&P 500 and Nasdaq 100 while sitting in India, there is a simpler route.
You may not need to open a US brokerage account or manage several layers of account administration and fees.
We can help you access these global indices through a simpler route, directly from India.
Want to know how it works? Get in touch with us.

4. India has the growth. The price is the question.
India continues to have several strong long-term drivers:
- Domestic demand
- Formalisation
- Manufacturing
- Infrastructure
- Financialisation
- Rising household participation in financial markets
The challenge is the price investors are paying for that growth.
India’s forward valuation remains at a premium to broader emerging markets:
| Index | Forward P/E |
|---|---|
| Nifty 50 / MSCI India | 19.9x to 21.3x |
| MSCI Emerging Markets | 15.0x |
| MSCI EM ex-China | 15.2x |
| S&P 500 | 19.4x to 24.6x |
India’s valuation premium over MSCI Emerging Markets remains around 1.35x to 1.40x.
That premium requires strong and consistent earnings growth.
The recent earnings record has been mixed:
- FY25 Nifty EPS growth: 3.4%
- FY26 Nifty EPS growth: 4.5%
- FY27 consensus EPS growth: 17.1%
- Recent forward estimate revision: approximately 0.9% downward
The broader listed universe has reportedly been growing at around 15% year on year, ahead of headline Nifty earnings growth.
This creates an important distinction between the index and individual businesses.
India can continue to grow strongly while equity returns remain modest if valuations already reflect a large part of the expected growth.
Higher US yields and FII flows
FII flows have become an important part of the Indian market discussion.
Foreign portfolio investors sold approximately ₹2.67 lakh crore to ₹2.74 lakh crore of Indian equities in H1 2026, equivalent to around $29.3 billion.
That exceeded total equity outflows for the whole of 2025, which were approximately ₹1.66 lakh crore.
At the same time, foreign investors brought around ₹63,784 crore into Indian fixed-income markets during H1 2026, supported by demand through the Fully Accessible Route.
This shows that foreign capital is not leaving India in one uniform direction.
FII equity allocations and debt allocations can move differently depending on yields, valuations, currency expectations and risk.
For example, higher US yields may make US fixed income more attractive, while Indian debt can still attract foreign capital when investors find the yield, currency outlook and risk-adjusted return appealing.
Therefore, FII selling in equities should not automatically be interpreted as a complete loss of confidence in India.
It may reflect:
- Relative valuation differences
- Attractive yields in developed markets
- Currency concerns
- Profit booking
- Portfolio rebalancing
- A preference for Indian debt over Indian equities
The more important question is whether FII selling is temporary and valuation-driven or reflects a deeper deterioration in earnings expectations and macroeconomic conditions.
Oil, dollar and the rupee
India imports approximately 87% to 88% of its crude oil requirement.
Brent crude has been trading around $97 to $100 per barrel amid geopolitical tensions.
A crude price above $100 combined with USD/INR above ₹95 can increase India’s import bill, pressure the current account and create additional challenges for the rupee.
The macro equation is therefore:
Higher oil prices + weaker rupee + higher US yields = greater pressure on Indian assets
This combination can make the work of the Reserve Bank of India more complicated. Higher imported inflation can limit policy flexibility, while weaker currency conditions can influence foreign investor sentiment.
For equity investors, the impact can appear through:
- Higher input costs
- Pressure on profit margins
- Weaker consumer purchasing power
- Higher funding costs
- Reduced foreign investor appetite
- Greater volatility in interest-rate-sensitive sectors
5. India vs US is the wrong portfolio question
The better question is:
What does each market contribute to the portfolio?
India
India provides exposure to:
- Domestic economic growth
- Rupee-linked assets
- Consumption
- Financialisation
- Manufacturing
- Infrastructure
- Long-term earnings growth
US
The US provides exposure to:
- Global businesses
- Technology
- AI
- Semiconductors
- Cloud computing
- Consumer platforms
- Healthcare innovation
- Dollar assets
The two markets also respond differently to economic conditions.
Higher US yields can pressure US equity valuations, particularly in long-duration growth stocks. At the same time, higher yields can support the dollar and direct capital toward US assets.
India can continue to deliver strong economic growth, while its valuation premium may become harder to sustain without corresponding earnings growth.
The portfolio decision should therefore consider:
- Business exposure
- Currency exposure
- Valuation
- Earnings growth
- Interest-rate sensitivity
- Investment horizon
- Liquidity needs
A portfolio built entirely around India can miss global technology and currency exposure.
A portfolio built entirely around the US can miss India’s domestic growth and rupee-linked opportunities.
Diversification works when the assets contribute different sources of return and respond differently to economic conditions.
The objective is not to hold two markets simply for the sake of diversification. The objective is to understand why each market is owned and what role it plays.
6. What should an Indian investor do now?
Keep India as the core
India remains an important part of a long-term portfolio because of its economic potential and domestic demand.
At elevated valuations, selectivity matters.
Investors may benefit from focusing on businesses with strong balance sheets, sustainable cash flows and reasonable earnings expectations. Experienced fund managers and individual company research can be useful when broad market returns become less predictable.
The focus should remain on business quality rather than short-term FII activity alone.
FII flows can influence prices in the near term, but long-term returns are ultimately connected to earnings, cash generation, capital allocation and the price paid for those businesses.
Keep global equity exposure
Global equity exposure can provide access to businesses and sectors that are limited or unavailable in India at comparable scale.
The US can play that role through the S&P 500, Nasdaq 100 and individual global companies.
The AI trade deserves attention, but buying purely after a strong rally can create valuation risk.
Track:
- Earnings growth
- Cash flow
- Capital expenditure
- Profit margins
- Valuation
- Business durability
The strongest global businesses can still be poor investments when purchased at unreasonable valuations.
Similarly, a market correction does not automatically make every company attractive. Investors should assess whether the underlying earnings outlook has improved, weakened or remained unchanged.

Give debt a role again
India’s 10-year government bond yield is around 6.96%, compared with approximately 4.96% for the US 10-year Treasury.
The India-US 10-year yield spread has narrowed to around 200 basis points, compared with historical cushions of approximately 300 to 400 basis points.
Indian fixed income still offers meaningful yields, especially for domestic investors.
| Instrument | Yield / spread |
|---|---|
| Two-year government bond yield | 6.10% |
| Five-year government bond yield | 6.54% |
| Ten-year government bond yield | 6.96% |
| AAA corporate bond spread | 50 to 85 basis points |
| CPI | 3.2% to 3.5% |
For investors with suitable time horizons, high-quality debt can provide income, portfolio stability and an opportunity to lock in yields.
Debt also becomes more relevant when equity valuations are elevated and market narratives are becoming increasingly dependent on future growth.
A balanced portfolio can use debt for stability, Indian equities for domestic growth and global equities for international business and currency exposure.
You don’t have to pick a winner
The next phase of markets may be less forgiving of easy narratives.
Higher US yields can pressure equity valuations. A stronger dollar can influence capital flows and put pressure on the rupee. India can continue to grow while its valuation premium limits future returns.
At the same time, strong US corporate earnings can support US equities even when rates are higher.
For an Indian investor, the portfolio lesson is straightforward:
India will continue to be part of the portfolio. Global equity exposure should be part of it too.
The objective is not to predict which market will perform better over the next twelve months.
It is to own good businesses across markets, pay attention to valuations, keep debt in the allocation and allow diversification to work across economic and currency cycles.
FII flows will continue to influence short-term market movements, but they should be treated as one input in the investment process rather than the entire investment thesis.
Markets are changing quickly, and the hardest part is often knowing what actually matters for your portfolio.
Join our 2,000+ member investor community, where we discuss Indian and global markets, investment opportunities, businesses and the ideas that can shape long-term portfolios.
If you’re looking to invest with more context and build stronger conviction, come join us.
Join the truwealth.club investor community.
As global markets respond to higher yields, currency movements and changing investor preferences, understanding how different assets fit together becomes increasingly important. For a deeper look at how art can fit into an investor’s broader allocation, read Art Market and how retail Investors can participate. Click here to read it.
As US bond yields, FII flows and global market valuations continue to shape portfolio decisions, this analysis was covered in our newsletter yesterday. If you’d like to receive such insights early, directly in your inbox, Click here to subscribe.